
Why Do Ethics and Sustainability Belong in a Strategy Course?
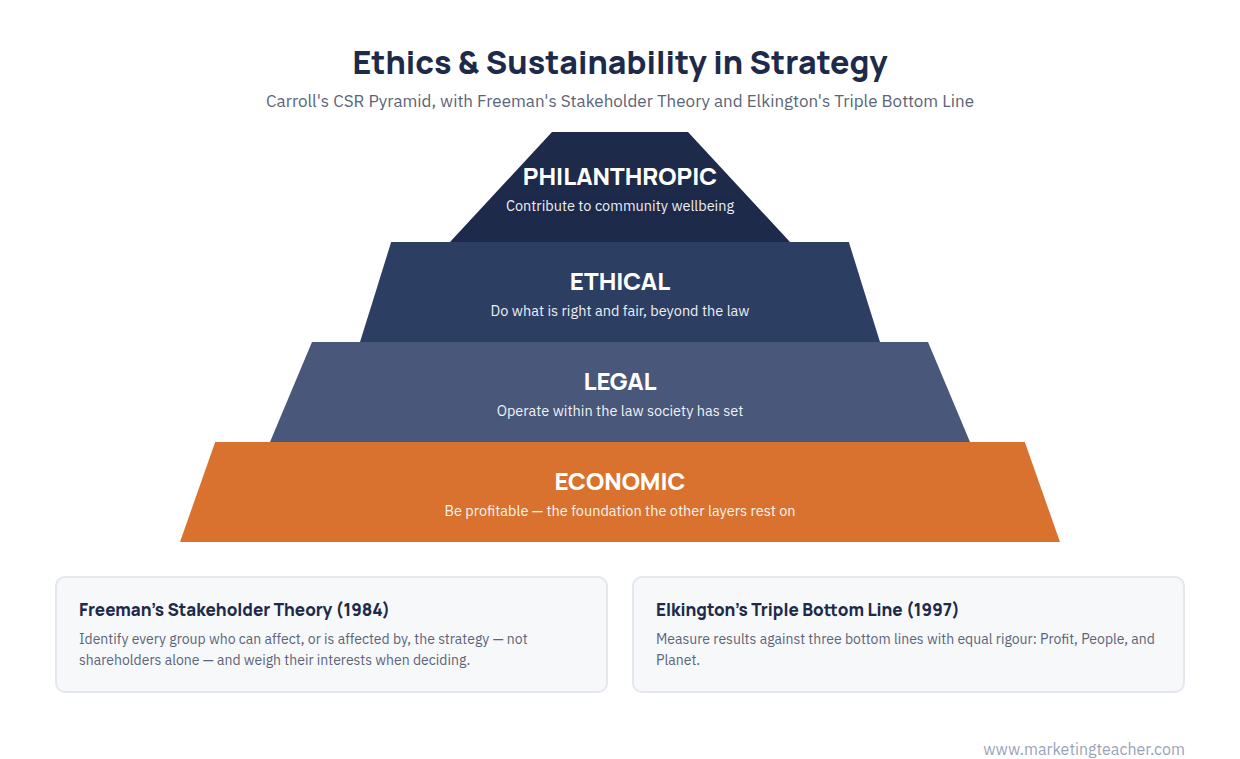
It is tempting to treat ethics and sustainability as compliance issues, handled by a legal team or a corporate responsibility department once the “real” strategy has already been decided. Three influential frameworks argue the opposite: how a business treats the people and interests affected by its decisions is itself a strategic choice, with consequences for reputation, cost of capital, regulation, employee retention, and long-run competitive position. Carroll’s CSR Pyramid, Freeman’s Stakeholder Theory, and Elkington’s Triple Bottom Line each give managers a different way to bring that choice into the strategy process, rather than leaving it to be decided informally after the fact.
Carroll’s CSR Pyramid
Carroll (1991) organised corporate social responsibility into four layers, stacked as a pyramid because each layer is meant to rest on the ones below it rather than replace them. At the base sits the economic responsibility: a business must be profitable, since an unprofitable business cannot sustain any of its other obligations. Above that sits the legal responsibility: operating within the law that society has set as the minimum acceptable standard. The third layer is the ethical responsibility: doing what is right and fair even where the law is silent or has not yet caught up with changing expectations. At the top sits the philanthropic responsibility: voluntarily contributing resources to improve the wellbeing of the community, which Carroll treated as desirable but the least obligatory of the four.
The pyramid’s usefulness for strategy is in the ordering: a business that pursues philanthropic activity while cutting corners legally, or that claims ethical intent while operating at a loss it cannot sustain, is building on a foundation that will not hold. Strategic decisions about corporate responsibility should generally secure the lower layers before investing heavily in the upper ones.
Freeman’s Stakeholder Theory
Freeman (1984) challenged the narrower view that a firm’s strategic obligation runs only to its shareholders. He defined a stakeholder as any group or individual who can affect, or is affected by, the achievement of an organisation’s objectives — a list that typically includes shareholders, employees, customers, suppliers, local communities, and government. Stakeholder theory asks managers to map who these groups are, what they want from the business, and how much influence each one has, then to weigh those competing interests explicitly when a strategy is being formed rather than discovering the conflicts only after the strategy is underway.
This reframes several tools already covered in this course. A Five Forces analysis of supplier and buyer power, for instance, is really examining two stakeholder groups through a competitive lens; stakeholder theory asks the broader question of how the business’s strategy affects — and is affected by — every group with a stake in the outcome, competitive or not.
Elkington’s Triple Bottom Line
Elkington (1997) proposed that businesses should measure and report their performance against three bottom lines rather than one: profit (the conventional financial measure), people (the social impact on employees, customers, and communities), and planet (the environmental impact of operations). The framework’s contribution to strategy is less the three categories themselves and more the insistence that all three be measured with the same discipline traditionally reserved for profit — vague commitments to “doing good” are treated as a strategic weakness, since what is not measured is rarely managed.
Worked Example: A Fictional Furniture ManufacturerConsider a fictional furniture manufacturer, Alderwood & Co. Applying Carroll’s pyramid, Alderwood first confirms its core furniture ranges are consistently profitable (economic) and that its timber sourcing and factory safety practices comply fully with regulation (legal), before expanding a voluntary community woodworking apprenticeship (philanthropic) it had been considering. Applying stakeholder theory, Alderwood maps its key stakeholders and identifies that a planned factory expansion would affect a nearby residential community more than any other group, so it consults that community before finalising the plan rather than after. Applying the triple bottom line, Alderwood begins reporting the proportion of timber sourced from certified sustainable forestry (planet) and staff turnover rates (people) alongside its usual financial results (profit), so all three are tracked with equal rigour.
Putting the Three Frameworks Together
The three frameworks work at different levels rather than competing with each other. Carroll’s pyramid asks what kinds of responsibility a business owes and in what order of priority; Freeman’s stakeholder theory asks whose interests need to be identified and weighed when a strategic decision is made; and Elkington’s triple bottom line asks how the results of that decision should be measured and reported. Used together, they connect back to tools already covered in this course: a stakeholder map can sharpen a Five Forces analysis by clarifying whose bargaining power actually matters, a chosen generic strategy should be checked against all three CSR layers before it is finalised, and a Balanced Scorecard can be extended with people and planet measures alongside its financial, customer, process, and learning perspectives.
Summary
Carroll (1991) organised corporate social responsibility into economic, legal, ethical, and philanthropic layers, with each layer resting on the ones beneath it. Freeman (1984) argued that strategy must account for every stakeholder group affected by, or able to affect, the organisation’s objectives, not shareholders alone. Elkington (1997) proposed measuring performance against three bottom lines — profit, people, and planet — with the same rigour traditionally reserved for financial results. Together, the three frameworks give strategists a way to decide what responsibilities to prioritise, whose interests to weigh, and how to measure the outcome.
The slides, worksheet, lesson plan and poster for this lesson are free to download and free to use in your course — no sign-up, no permission needed.

